

Can you get a HELOC with bad credit? The answer is that it depends on several factors, like your lender’s requirements, the amount of equity you have in your home, your income, your debt-to-income ratio, and more. Your credit score is only one part of your HELOC application. That said, most lenders prefer applicants with scores of 620 or above.
If you’re not sure if you qualify for a HELOC, below is more information about your approval odds based on your credit score. We’ll also answer frequently asked questions and share alternatives to consider.
Key Takeaways
- Most lenders prefer credit scores of 620 or above for HELOC borrowers, but there are steps you can take to improve your credit score quickly.
- Lenders consider several factors when determining whether or not to approve you for a HELOC, including your income, payment history, and how much home equity you have.
- There are other types of home equity products you may qualify for if you don’t get approved for a HELOC, like a home equity agreement.
See which home equity options fit your credit score
Your credit score can affect which home equity products and lenders may be available to you. Select your range to see information tailored to your credit profile.
Selecting your credit score range here won’t affect your credit score.
Tool Disclaimer
This quiz is intended to help illustrate options a user may have based on available aggregate data, but it does not include every possible option.
Results from this quiz should not be considered a guarantee of approval or denial for any product. Each provider will have their own specific application procedures and eligibility requirements.
Note: Credit score requirements vary by lender, and you may need a higher score for larger lines of credit or to secure the lowest rates. If your score is higher than 580, see our highest-rated HELOCs for fair credit. Below 580, look into home equity agreements as an alternative.
Can you get a HELOC with a 500 credit score?
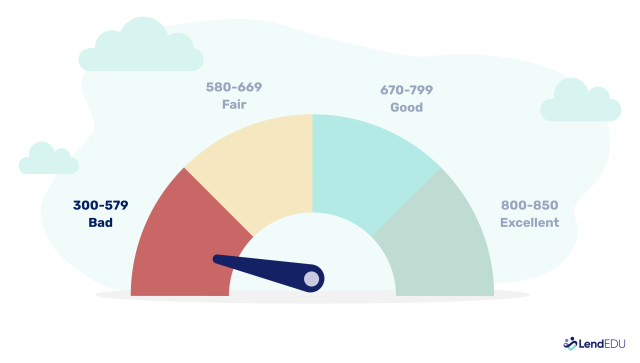
HELOCs tend to be a riskier product for lenders. They are more complex than a personal loan because HELOCs are tied to your home. They also tend to have variable interest rates and flexible draw periods. Because of that, it’s less predictable how (and when) borrowers will use and repay the money.
Because of that, lenders tend to set the bar high. After all, they want to make sure that you have a proven track record of managing debt responsibly. A credit score in the 500s shows that in the past, you may have had late payments, defaults, or high credit utilization, all of which make you a riskier borrower in lenders’ eyes. From their perspective, it may be too risky to offer a line of credit secured by your home without a stronger credit profile.
If you still want to get a HELOC, take some steps to improve your credit. Most lenders require a minimum credit score of 620 to consider your application, and even then, approval isn’t guaranteed. We’ve reviewed HELOCs for fair credit if you’re in the rebuilding phase and want to explore your options.
In general, lending has become tighter since 2021; interest rates have risen due to the Federal Reserve raising rates. In an effort to avoid an environment similar to the 2007 to 2009 Great Recession and housing crisis, lenders—particularly with first and second mortgages—want to ensure they’re loaning to reliable borrowers.

HELOC approval odds by score
Getting a HELOC for bad credit is rare, as that typically refers to scores between 300 and 579. If you’re in this range, getting approved for a traditional HELOC is unlikely, even if you have a good income and substantial equity in your home.
Here’s how approval odds break down at the lower end of the credit spectrum:
| Credit score | Realistic approval odds | What to expect |
| 300–499 | Very unlikely | Most lenders won’t consider credit scores in this range. Take some time to focus on rebuilding your credit first. |
| 500-579 | Unlikely | It’s unlikely to be approved for a HELOC with this range of credit score, but improving your score above 600 could help. |
| 580-599 | Limited | Approval is still challenging in this score range. Keep focusing on improving your credit score. |
| 600-619 | Possible with certain lenders | Some lenders do consider scores starting at 600 if you have other strong factors, like income and significant home equity. |
| 620-679 | Possible | Many lenders consider a 620 a minimum credit score to consider HELOC applications. |
| 680+ | Better approval odds | If you have enough equity, manageable debt, and a stable income, more lenders may consider you for a HELOC. |
How does a low credit score affect your HELOC?
If you can boost your credit score enough to be approved for a HELOC, it’s important to know how a lower score can affect the loan terms. Getting a HELOC for bad credit will likely mean paying a higher interest rate, making your credit line more expensive.
Interest rates for many HELOCs are variable and based on the federal prime interest rate. The lender takes the prime rate and adds a margin based on your perceived creditworthiness; the higher the risk, the higher the margin. That equals more interest paid on the loan.
Here’s how it works:
- Anna has a good credit score of 780: The lender offers her a rate of prime plus 2%. At a prime of 8%, that equals a 10% interest rate. On a $50,000 HELOC with a draw period of five years, Anna will pay $25,000 in interest if she takes out the entire $50,000 at the beginning of the draw period (assuming no change in the prime interest rate and no principal payments while she’s in the draw period).
- Brian has a fair credit score of 620: His lender offers a rate of prime plus 6% for a total of 14%. On the same $50,000 HELOC withdrawn at the beginning of the five-year draw period, Brian will pay $35,000 in interest, $10,000 more than Anna.
Here’s how the different interest rates affect the total cost of a $50,000 HELOC over five years:
| Borrower | Credit score | Interest rate | 5-year interest |
| Anna | 780 | 10% | $25,000 |
| Brian | 620 | 14% | $35,000 |
| Additional interest paid by Brian | $10,000 |
Bad credit can also affect the size of your HELOC credit limit. To help mitigate risk, lenders will likely offer you a smaller line of credit compared to someone with good credit. Here’s an example of how this could play out:
- Anna, with a 780 credit score, has $200,000 equity in her home. Her lender may offer her a higher credit line because of that.
- Brian, with a 620 credit score, also has $200,000 equity in his home. To lower the risk, the lender may offer him a smaller credit line, even though he has the same amount of home equity as Anna.
Other terms, such as the length of your draw and repayment periods, could also be shortened because of bad credit. You might even pay an annual fee on the credit line to help compensate for the risk of lending.
Is there a HELOC for bad credit? Some websites or lenders may suggest you can get a HELOC with a 500 or 540 credit score, but this is highly misleading. These scores fall below even the most flexible lender minimums.
How to improve your approval odds for a HELOC with bad credit
Many lenders require a minimum score of 620 to apply for a HELOC. Here are a few ways you can improve your approval odds if you have a lower credit score:
- Pay down debt: Reducing your outstanding debt could boost your credit score by lowering your credit utilization ratio. Paying off debts would also reduce your DTI, making you a more attractive prospect to lenders.
- Increase home equity: Paying off more of your mortgage increases your home equity. More equity equals more collateral, which reduces lenders’ risk and improves your chances of getting approved for a HELOC.
- Check credit report for errors: Credit report errors can harm your score. Reviewing your reports for errors and disputing them with the credit bureau could improve your score if they correct and remove the errors.
- Consider a cosigner: A cosigner on a HELOC is someone who applies alongside you and assumes equal legal responsibility for the debt. A cosigner could bolster your application and help you qualify for better terms if they have a solid credit score.
Along with these tips, follow the usual best practices for improving a credit score. That includes paying bills on time, keeping older accounts open, and not applying for new credit that isn’t a necessity.
You could possibly renegotiate for a better HELOC rate down the road if you and a cosigner can prove that a past hardship caused your credit rating to decline and reflect poorly on your credit report. Examples could include divorce, unexpectedly needing to care for a family member (and using your savings or credit cards), filing for Chapter 7 bankruptcy, or you or your spouse losing your job, resulting in reduced overall income.
But keep in mind: You must prove you have recovered from this and have a reliable source of income. It’s worth a shot to negotiate—or wait to apply for a HELOC if it isn’t a critical need. In the meantime, you could build up savings and work on improving your credit score and credit report. You can also ask the lender what it recommends and wants to see improved on your credit report to approve your loan request.
Pros and cons of getting a HELOC with bad credit
Consider the advantages and disadvantages before trying to get a HELOC if you have bad credit.
Pros:
- Borrow as needed: You don’t need to withdraw the entire amount at once; you only take out funds when you need them.
- Flexible use of funds: You can use a HELOC for almost anything.
- Interest-only payments during draw period: Many HELOCs don’t require you to pay the principal balance during the draw period, which makes the debt easier to manage early.
- Potential for lower interest rates: Because most HELOCs offer variable interest, your rates could drop if the prime interest rate falls.
Cons:
- Higher interest rates: Borrowers with bad credit are more likely to pay higher interest rates, making your loan more expensive over time.
- Smaller credit limit: Lenders compensate for the high risk of lending by reducing the size of your home equity line of credit.
- Risk of losing your home: Because your home is collateral, you may lose it if you fail to make HELOC payments.
If I can’t get a HELOC with bad credit, what should I do instead?
If a HELOC isn’t in the cards due to bad credit, you still have options to tap into your home equity or access the cash you need.
1. Home equity agreement
A home equity agreement (HEA) lets you turn your equity into cash without taking on monthly payments or interest. Instead of borrowing money, you’re selling a share of your home’s future value in exchange for a lump sum today.
These agreements often have more flexible credit requirements than traditional loans, making them a potential fit for homeowners with lower scores.
2. Personal loan
Some lenders offer personal loans to borrowers with poor credit, though rates may be higher. If you don’t have enough home equity or prefer an unsecured option, a personal loan could help cover your expenses.
- Terms and conditions apply. SOFI RESERVES THE RIGHT TO MODIFY OR DISCONTINUE PRODUCTS AND BENEFITS AT ANY TIME WITHOUT NOTICE. To qualify, a borrower must be a U.S. citizen or other eligible status, be residing in the U.S., and meet SoFi’s underwriting requirements. Not all borrowers receive the lowest rate. Lowest rates reserved for the most creditworthy borrowers. If approved, your actual rate will be within the range of rates at the time of application and will depend on a variety of factors, including term of loan, evaluation of your creditworthiness, income, and other factors. If SoFi is unable to offer you a loan but matches you for a loan with a participating bank, then your rate may be outside the range of rates listed above. Rates and Terms are subject to change at any time without notice. SoFi Personal Loans can be used for any lawful personal, family, or household purposes and may not be used for post-secondary education expenses. Minimum loan amount is $5,000. The average of SoFi Personal Loans funded in 2025 was around $32K. Based on loans funded from 1/1/2025-12/31/2025. Information current as of 10/02/26. SoFi Personal Loans originated by SoFi Bank, N.A. Member FDIC. NMLS #696891 (www.nmlsconsumeraccess.org). See SoFi.com/legal for state-specific license details. See SoFi.com/eligibility for details and state restrictions.
- Fixed rates from 6.99% APR to 35.49% APR. APR reflect the 0.25% autopay interest rate discount and a 0.25% member rate discount. SoFi Platform personal loans are made either by SoFi Bank, N.A. or , Cross River Bank, a New Jersey State Chartered Commercial Bank, operating from its Delaware branch, Member FDIC, Equal Housing Lender. SoFi may receive compensation if you take out a loan originated by Cross River Bank. These rate ranges are current as of 10/02/26 and are subject to change without notice. Not all rates and amounts available in all states. See SoFi Personal Loan eligibility details at https://www.sofi.com/eligibilitycriteria/#eligibility-personal. Not all applicants qualify for the lowest rate. Lowest rates reserved for the most creditworthy borrowers. Your actual rate will be within the range of rates listed above and will depend on a variety of factors, including evaluation of your credit worthiness, income, and other factors. Loan amounts range from $5,000– $100,000. The APR is the cost of credit as a yearly rate and reflects both your interest rate and an origination fee of 9.99% of your loan amount for Cross River Bank originated loans which will be deducted from any loan proceeds you receive and for SoFi Bank originated loans have an origination fee of 0%-7%, will be deducted from any loan proceeds you receive.
- Autopay Discount: The SoFi 0.25% autopay interest rate reduction requires you to make monthly payments using SoFi’s automatic monthly deduction from a savings or checking account. The discount will discontinue and be lost when you do not have autopay enabled. You’re not required to set up autopay to obtain this loan.
- Member Rate Discount: To be eligible for an additional 0.25% interest rate reduction on a Personal Loan, you must, within 31 days of loan funding, either (1) meet SoFi Plus eligibility criteria, (2) receive an Eligible Direct Deposit into a SoFi Checking or Savings account, or (3) receive at least $5,000 in Qualifying Deposits into a SoFi Checking or Savings account. You must continue to meet at least one of the above eligibility criteria every 31 days to maintain the discount. See the SoFi Plus terms for details on SoFi Plus subscription. For more details on Eligible Direct Deposit or Qualifying Deposits, please see https://www.sofi.com/legal/banking-rate-sheet. Once you become eligible during the initial period, the discount will be removed or reinstated depending on whether the criteria have been met. Each time your loan is re-amortized, your monthly payment amount will change based upon the interest rate that was in place. SoFi reserves the right to modify or terminate this offer at any time for unenrolled participants. You are not required to meet these criteria to be approved for a loan.
- Terms and conditions apply. SOFI RESERVES THE RIGHT TO MODIFY OR DISCONTINUE PRODUCTS AND BENEFITS AT ANY TIME WITHOUT NOTICE. To qualify, a borrower must be a U.S. citizen or other eligible status, be residing in the U.S., and meet SoFi’s underwriting requirements. Not all borrowers receive the lowest rate. Lowest rates reserved for the most creditworthy borrowers. If approved, your actual rate will be within the range of rates at the time of application and will depend on a variety of factors, including term of loan, evaluation of your creditworthiness, income, and other factors. If SoFi is unable to offer you a loan but matches you for a loan with a participating bank, then your rate may be outside the range of rates listed above. Rates and Terms are subject to change at any time without notice. SoFi Personal Loans can be used for any lawful personal, family, or household purposes and may not be used for post-secondary education expenses. Minimum loan amount is $5,000. The average of SoFi Personal Loans funded in 2025 was around $32K. Based on loans funded from 1/1/2025-12/31/2025. Information current as of 10/02/26. SoFi Personal Loans originated by SoFi Bank, N.A. Member FDIC. NMLS #696891 (www.nmlsconsumeraccess.org). See SoFi.com/legal for state-specific license details. See SoFi.com/eligibility for details and state restrictions.
- Fixed rates from 6.99% APR to 35.49% APR. APR reflect the 0.25% autopay interest rate discount and a 0.25% member rate discount. SoFi Platform personal loans are made either by SoFi Bank, N.A. or , Cross River Bank, a New Jersey State Chartered Commercial Bank, operating from its Delaware branch, Member FDIC, Equal Housing Lender. SoFi may receive compensation if you take out a loan originated by Cross River Bank. These rate ranges are current as of 10/02/26 and are subject to change without notice. Not all rates and amounts available in all states. See SoFi Personal Loan eligibility details at https://www.sofi.com/eligibilitycriteria/#eligibility-personal. Not all applicants qualify for the lowest rate. Lowest rates reserved for the most creditworthy borrowers. Your actual rate will be within the range of rates listed above and will depend on a variety of factors, including evaluation of your credit worthiness, income, and other factors. Loan amounts range from $5,000– $100,000. The APR is the cost of credit as a yearly rate and reflects both your interest rate and an origination fee of 9.99% of your loan amount for Cross River Bank originated loans which will be deducted from any loan proceeds you receive and for SoFi Bank originated loans have an origination fee of 0%-7%, will be deducted from any loan proceeds you receive.
- Autopay Discount: The SoFi 0.25% autopay interest rate reduction requires you to make monthly payments using SoFi’s automatic monthly deduction from a savings or checking account. The discount will discontinue and be lost when you do not have autopay enabled. You’re not required to set up autopay to obtain this loan.
- Member Rate Discount: To be eligible for an additional 0.25% interest rate reduction on a Personal Loan, you must, within 31 days of loan funding, either (1) meet SoFi Plus eligibility criteria, (2) receive an Eligible Direct Deposit into a SoFi Checking or Savings account, or (3) receive at least $5,000 in Qualifying Deposits into a SoFi Checking or Savings account. You must continue to meet at least one of the above eligibility criteria every 31 days to maintain the discount. See the SoFi Plus terms for details on SoFi Plus subscription. For more details on Eligible Direct Deposit or Qualifying Deposits, please see https://www.sofi.com/legal/banking-rate-sheet. Once you become eligible during the initial period, the discount will be removed or reinstated depending on whether the criteria have been met. Each time your loan is re-amortized, your monthly payment amount will change based upon the interest rate that was in place. SoFi reserves the right to modify or terminate this offer at any time for unenrolled participants. You are not required to meet these criteria to be approved for a loan.
- Terms and conditions apply. SOFI RESERVES THE RIGHT TO MODIFY OR DISCONTINUE PRODUCTS AND BENEFITS AT ANY TIME WITHOUT NOTICE. To qualify, a borrower must be a U.S. citizen or other eligible status, be residing in the U.S., and meet SoFi’s underwriting requirements. Not all borrowers receive the lowest rate. Lowest rates reserved for the most creditworthy borrowers. If approved, your actual rate will be within the range of rates at the time of application and will depend on a variety of factors, including term of loan, evaluation of your creditworthiness, income, and other factors. If SoFi is unable to offer you a loan but matches you for a loan with a participating bank, then your rate may be outside the range of rates listed above. Rates and Terms are subject to change at any time without notice. SoFi Personal Loans can be used for any lawful personal, family, or household purposes and may not be used for post-secondary education expenses. Minimum loan amount is $5,000. The average of SoFi Personal Loans funded in 2025 was around $32K. Based on loans funded from 1/1/2025-12/31/2025. Information current as of 10/02/26. SoFi Personal Loans originated by SoFi Bank, N.A. Member FDIC. NMLS #696891 (www.nmlsconsumeraccess.org). See SoFi.com/legal for state-specific license details. See SoFi.com/eligibility for details and state restrictions.
- Fixed rates from 6.99% APR to 35.49% APR. APR reflect the 0.25% autopay interest rate discount and a 0.25% member rate discount. SoFi Platform personal loans are made either by SoFi Bank, N.A. or , Cross River Bank, a New Jersey State Chartered Commercial Bank, operating from its Delaware branch, Member FDIC, Equal Housing Lender. SoFi may receive compensation if you take out a loan originated by Cross River Bank. These rate ranges are current as of 10/02/26 and are subject to change without notice. Not all rates and amounts available in all states. See SoFi Personal Loan eligibility details at https://www.sofi.com/eligibilitycriteria/#eligibility-personal. Not all applicants qualify for the lowest rate. Lowest rates reserved for the most creditworthy borrowers. Your actual rate will be within the range of rates listed above and will depend on a variety of factors, including evaluation of your credit worthiness, income, and other factors. Loan amounts range from $5,000– $100,000. The APR is the cost of credit as a yearly rate and reflects both your interest rate and an origination fee of 9.99% of your loan amount for Cross River Bank originated loans which will be deducted from any loan proceeds you receive and for SoFi Bank originated loans have an origination fee of 0%-7%, will be deducted from any loan proceeds you receive.
- Autopay Discount: The SoFi 0.25% autopay interest rate reduction requires you to make monthly payments using SoFi’s automatic monthly deduction from a savings or checking account. The discount will discontinue and be lost when you do not have autopay enabled. You’re not required to set up autopay to obtain this loan.
- Member Rate Discount: To be eligible for an additional 0.25% interest rate reduction on a Personal Loan, you must, within 31 days of loan funding, either (1) meet SoFi Plus eligibility criteria, (2) receive an Eligible Direct Deposit into a SoFi Checking or Savings account, or (3) receive at least $5,000 in Qualifying Deposits into a SoFi Checking or Savings account. You must continue to meet at least one of the above eligibility criteria every 31 days to maintain the discount. See the SoFi Plus terms for details on SoFi Plus subscription. For more details on Eligible Direct Deposit or Qualifying Deposits, please see https://www.sofi.com/legal/banking-rate-sheet. Once you become eligible during the initial period, the discount will be removed or reinstated depending on whether the criteria have been met. Each time your loan is re-amortized, your monthly payment amount will change based upon the interest rate that was in place. SoFi reserves the right to modify or terminate this offer at any time for unenrolled participants. You are not required to meet these criteria to be approved for a loan.
Compare the best personal loans
3. Cash-out refinance
If you’ve built substantial equity and your credit isn’t severely damaged, a cash-out refinance could be another route. This replaces your existing mortgage with a new, larger loan—and gives you the difference in cash. (If you currently have a low mortgage rate, this may not be the best option for you.)
Explore the best cash-out refinance options
4. Loan from a family member or friend
If none of the above are workable, consider asking someone you trust for a private loan. It may not be ideal, but it could buy you time to improve your credit and qualify for better financing in the future.
No matter which option you choose, the key is to avoid predatory lenders and high-cost products that can trap you in a cycle of debt. Focus on rebuilding your credit so that more favorable options—like a HELOC—become available down the line.
HELOCs for bad credit FAQ
What disqualifies you for a HELOC?
Several factors can disqualify you from getting a HELOC, including a low credit score (e.g., below a lender’s minimum requirement), high debt-to-income ratio (DTI), insufficient home equity, inconsistent income, or a history of late payments, foreclosures, or bankruptcies.
What would cause a HELOC to be denied?
A HELOC could be denied if you have insufficient home equity, high DTI, a poor credit history with recent delinquencies, unstable income, or if your property has significant issues that affect its value. The application could be rejected if you don’t meet a lender’s specific requirements, such as minimum income levels.
Does a HELOC damage your credit?
Applying for a HELOC typically involves a hard credit inquiry, which can lower your credit score by a few points. Once approved, responsibly managing the HELOC, such as making on-time payments, can help improve your credit over time. However, missing payments or overextending your credit can damage your score.
What is the best HELOC for a 500 credit score?
Unfortunately, most lenders will not approve a HELOC if you have a 500 credit score. If you’re looking for the best HELOC for bad credit borrowers, your best bet is to either work on increasing your credit score or consider an alternative, like a Home Equity Agreement.
What is the lowest credit score for a HELOC?
Typically, borrowers need a minimum credit score of at least 620 to be considered for a HELOC, though some lenders may accept as low as 600. Other HELOC requirements include having stable income, enough home equity, and a low debt-to-income ratio.
How we researched HELOC options for bad credit
Since 2018, LendEDU has evaluated home equity companies to help readers find the best home equity loans and HELOCs. Our latest analysis reviewed 850 data points from 34 lenders and financial institutions, with 25 data points collected from each. This information is gathered from company websites, online applications, public disclosures, customer reviews, and direct communication with company representatives.
These star ratings help us determine which companies are best for different situations. We don’t believe two companies can be the best for the same purpose, so we only show each best-for designation once.
Bottom line: Can you get a HELOC with bad credit?
Getting a HELOC with bad credit can be challenging, especially if your credit score is below 600. Most lenders prefer scores of at least 620, but your income, existing debt, and available home equity also play a role in determining your eligibility.
If your credit score is too low to qualify for a traditional HELOC, you may still have options. Home equity agreements (HEAs), for example, may have more flexible credit requirements and offer another way to access your home’s equity without taking on monthly loan payments.
About our contributors
-
 Written by Rebecca Lake, CEPF®
Rebecca Lake is a certified educator in personal finance (CEPF®) and freelance writer specializing in finance.
-
 Edited by Amanda Hankel
Amanda Hankel is a managing editor at LendEDU. She has more than seven years of experience covering various finance-related topics and has worked for more than 15 years overall in writing, editing, and publishing.